Why LOAN SERVICING SOFT's Line of Credit Functionality Make It Better For Private Money Lending
It's All About Flexibility and Control
Private Money and Hard Money lenders operate in a market defined by flexibility and control. Unlike conventional mortgage originators, who service largely standardized, single draw, amortizing products, private and hard money lenders routinely fund construction loans, fix-and-flip bridge loans, and revolving business lines of credit that disburse in stages rather than in a single lump sum. Servicing this kind of loan portfolio with spreadsheets or with software built primarily for fixed-rate, amortized, single draw mortgages quickly becomes unworkable. LOAN SERVICING SOFT (LSS), a loan servicing and origination platform built on more than 40 years of industry experience, was designed from the ground up to handle exactly this kind of complexity. Among its core capabilities, native support for lines of credit and multi-draw loans stands out as a defining strength, and it is a primary reason the platform has become a leading choice for private money lenders. This paper examines how LSS's line of credit functionality works, how it is woven into the rest of the platform, and why that combination gives private lenders a servicing advantage that generic or conventional systems cannot match.
The Private Lending Challenge with Revolving and Multi-Draw Credit
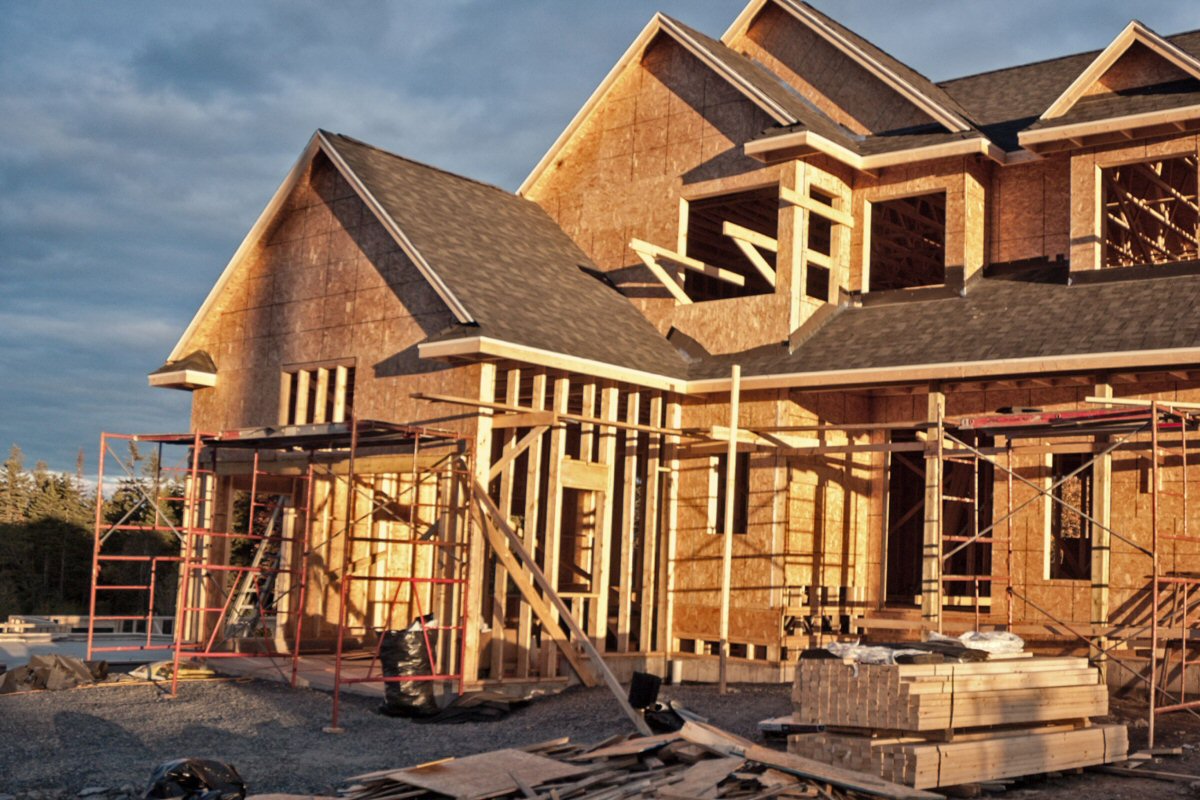
Lines of credit and multi-draw loans are structurally different from a standard installment loan. A borrower may be approved for a maximum credit limit but draws against it incrementally — for example, a builder drawing funds at each stage of a construction project, or a business owner drawing operating capital as needed and repaying it on a revolving basis. Every draw changes the outstanding principal balance, which in turn changes the interest accrual, the borrower's available credit, the investor's funded exposure. Handling this manually, or with a system designed only for closed-end fixed loans, invites miscalculation, delayed funding, and reconciliation headaches. LOAN SERVICING SOFT has addressed this complexity by directly building line of credit functionality, for both interest only and amortized loan models, into its core loan engine rather than treating these models as an afterthought or a workaround.
Native, Built-In Support for Credit Lines and Multi-Draw Loans
LOAN SERVICING SOFT is specifically designed to manage Credit Lines, Revolving Credit Lines and Multi-Draw loans alongside Term Loans, Fixed Rate, Step-Rate, and ARM models. This means a lender does not need a separate module, a third-party add-on, or manual spreadsheet work a rounds to service these loam models. All loan models are configured within the same system. With lines of credit draws increase the outstanding balance and are tracked with precision, giving lenders real-time visibility into how much of a borrower's approved limit has been disbursed and how much remains available. For construction and fix-and-flip lenders in particular, this draw-schedule tracking allows funds to be released against project milestones while the system keeps balances, accrued interest, and available credit continuously up to date, reducing the risk of miscalculation that grows with every added draw or disbursement.
Flexible Interest Calculation Built for Variable-Balance Lending
A revolving balance only works if the interest calculation engine can keep pace with it. Because the principal on a line of credit rises and falls unpredictably, interest must be computed against a constantly changing balance rather than a fixed amortization schedule. LOAN SERVICING SOFT supports multiple interest calculation methods — including simple interest, regular periodic, actual days, and Rule 78 — giving lenders the flexibility to select the method that fits the specific structure of a given credit line or multi-draw loan. This matters because private lenders often price and structure credit facilities differently from one deal to the next; a system limited to a single amortization method simply cannot keep up with that variability. By pairing native line-of-credit and multi-draw loan types with configurable interest methods, LOAN SERVICING SOFT ensures that accrued interest, payoffs, and statements remain accurate no matter how a borrower draws against or repays the facility.
Automated Accounting and Investor Management for Revolving Portfolios
Private lenders rarely fund loans with a single source of capital. Lines of credit and multi-draw loans are frequently backed by multiple investors or pooled funding sources, and every draw or paydown has to be allocated correctly across those participants. LOAN SERVICING SOFT's automated accounting engine is built to handle exactly this scenario, supporting multiple investors and funding pools alongside private-money-specific tools such as servicing fees and bought/sold rate tracking. General ledger entries, accruals, and investor payments — whether by batch check or ACH — are generated automatically as draws and payments post, and the platform's QuickBooks interface allows those entries to flow straight into a general ledger without duplicate data entry. For a revolving line where balances change frequently, this automation is what keeps investor statements, trust accounting, and compliance reporting synchronized with the loan's actual activity, rather than lagging behind it.
Borrower Self-Service and Draw Requests Through Web Portals
LOAN SERVICING SOFT extends its line of credit functionality to the borrower experience as well. The platform's live, customizable web portals give borrowers 24-hour access to their account, including payment history and the next payment due, and the optional self-service application button allows borrowers to apply for new loans, request loan extensions, or draw against a line of credit directly through their web portal. Because the portal is tied into LOAN SERVICING SOFT's built-in CRM/contact manager, a draw request or new application flows straight into the lender's servicing system rather than arriving as a phone call or an email that has to be manually keyed in. Combined with text-to-ACH payment reminders and one-time ACH or credit card payment processing, this self-service layer reduces the operational burden on lending staff while giving borrowers the immediate access they expect from a revolving credit product.
Workflow and Role-Based Controls
Managing a portfolio of revolving credit lines also means managing tasks like inspections and other due diligence items. LOAN SERVICING SOFT's workflow and task management tools, built on Microsoft's role based security architecture, let lenders route draw approvals, alerts, and tasks to specific users or departments, ensuring that every disbursement passes through the appropriate review before funds move.
Forty Years of Purpose-Built Experience
What really differentiates LOAN SERVICING SOFT's line of credit functionality is its more than 40 years of loan and mortgage industry knowledge, built specifically for private money, hard money, and alternative lending.. That history shows up in the details that matter for revolving and multi-draw line of credit lending: draw tracking that keeps pace with construction milestones, an interest engine built to handle fluctuating daily principal balances, investor accounting that reflects multiple funding sources, and a technical team experienced enough to support lenders through the edge cases that inevitably arise with non-standard credit facilities. For a private lender evaluating servicing platforms, that combination of purpose-built functionality and long-standing domain expertise is difficult for newer or more generalized competitors to replicate.
A Platform Trusted Across the Private Lending Industry
LSS's approach to line of credit servicing is reinforced by the breadth of organizations that rely on the platform, spanning private money funds, hard money lenders, community development lenders, and specialty finance companies. That range of customers reflects the same underlying strength discussed throughout this paper: a single, unified system that can service a fixed-rate bridge loan, a construction draw schedule, and a revolving line of credit side by side, without forcing a lender to maintain separate tools for each. For a private lender weighing servicing platforms, the practical question is rarely whether a system can handle a plain-vanilla installment loan — most can. The harder question is whether it can handle the revolving, multi-draw, multi-investor structures that make up a meaningful share of private lending volume, without custom development or manual work a rounds. LSS's answer to that question, built into the core of its loan-type engine rather than layered on top of it, is a central part of what has made it a recognized name in the space.
Conclusion
Lines of credit and multi-draw loans are among the most operationally demanding products a private lender services, precisely because they do not behave like a fixed, fully amortizing loan. LOAN SERVICING SOFT meets that demand with native support for credit lines and multi-draw structures, flexible interest calculation methods suited to fluctuating balances, automated multi-investor accounting, borrower self-service draw requests through branded web portals, role-based workflow controls, and compliance-ready reporting — all within a single platform backed by decades of industry-specific experience. Rather than treating revolving credit as a niche add-on, LSS builds it into the core of the system, which is precisely what allows the platform to describe itself as an ideal loan servicing solution for private, alternative lenders whose portfolios depend on exactly this kind of flexibility.
Ready to learn more? Let's explore how LOAN SERVICING SOFT can transform your operation.. Reach out today and Let's talk!